

Having diabetes does not automatically prevent you from getting life insurance in Canada. Depending on your type of diabetes, how long you have had it, how well it is controlled, your treatment, and your overall health, you may qualify for traditional life insurance, simplified issue coverage, or guaranteed issue insurance.
If you are looking for life insurance with diabetes, the right option depends on your individual circumstances. Our independent, licensed brokers compare life insurance options from more than 20 Canadian providers, including options for applicants with pre-existing health conditions. Instead of applying to just one insurer, you can compare your options and find coverage that fits your needs and budget.
Find out more about your options below.
Get your quote for life insurance for diabetes patients
Examples of life insurance policies for diabetes patients
Person:
44, female, non-smoker, diabetes type II, non-insulin-dependent, diagnosed 5 years ago, stable blood sugar reading, Term 20 policy, $250,000 coverage
Estimated monthly rate:
$56.43
Person:
38, male, non-smoker, diabetes type I, insulin-dependent, diagnosed 7 years ago, stable blood sugar reading, Term 20 policy, $500,000 coverage
Estimated monthly rate:
$123.48
Person:
51, female, smoker, diabetes type II, non-insulin-dependent, diagnosed 10 years ago, stable blood sugar reading, Term 10 policy, $200,000 coverage
Estimated monthly rate:
$93.69
Life Insurance and Diabetes: Can You Get Covered?
Yes. Many people with Type 1 or Type 2 diabetes can qualify for life insurance. However, diabetes can affect both the type of coverage available and the rate you pay.
With traditional life insurance, an insurer may consider your type of diabetes, age when you were diagnosed, treatment, A1C and blood sugar control, and any diabetes-related complications. Depending on the results of the underwriting process, you could qualify for a preferred or standard rate, receive a rated offer with a higher premium, or be declined.
If traditional coverage is not available, no-medical options may provide another way to obtain life insurance. Simplified issue policies require less medical information, while guaranteed issue policies generally do not require medical underwriting. These options can be more expensive than fully underwritten coverage.
If you have prediabetes rather than diagnosed diabetes, your insurance options may be different. In some cases, you may still qualify for traditionally underwritten coverage.
Life Insurance for Someone with Diabetes: What Are Your Options?
There are several types of life insurance that may be available to someone with diabetes. Your options depend on your type of diabetes, health history, and the insurer’s underwriting guidelines.
| Type of insurance | Type 1 diabetes | Type 2 diabetes |
|---|---|---|
| Traditional without underwriting | Not Available | Not Available |
| Traditional with underwriting | Can be available, but underwriting may be more detailed | Depending on health and diabetes control |
| Simplified | Can be an option with higher rates | Can be an option with higher rates |
| Guaranteed | Generally an option, but rates are very high | Generally an option, but rates are very high |
Traditional life insurance normally involves medical underwriting. Because the insurer has more information about your health, it may be possible to obtain lower rates than with no-medical coverage, particularly when diabetes is well controlled.
Simplified issue life insurance involves fewer health questions and generally does not require a medical exam. Because the insurer has less information with which to assess your health, premiums are generally higher than for fully underwritten coverage.
Guaranteed issue life insurance is designed for applicants who may have difficulty qualifying for other types of coverage. It generally does not require medical questions or an exam, but premiums are typically higher and coverage amounts may be more limited.
The table above is a general guide rather than a guarantee of eligibility. Each insurer has its own underwriting guidelines, and your complete health history can affect the outcome.
Getting Life Insurance with Type 2 Diabetes
Type 2 diabetes does not automatically mean that you need a no-medical life insurance policy or that you will have to pay very high premiums.
If your diabetes is well controlled and you do not have significant complications, you may qualify for traditional life insurance. Depending on your overall health and the insurer’s guidelines, you may qualify for standard rates or another traditional rate class.
If traditional underwriting results in a higher premium or a decline, simplified issue and guaranteed issue policies can provide alternative options.
Life Insurance for Type 1 Diabetes
People with Type 1 diabetes can also qualify for life insurance, although traditional coverage may involve more detailed underwriting and, depending on the individual situation, a higher premium.
Insurers may consider how long you have had diabetes, your treatment, blood sugar control, and whether you have developed any complications. Some applicants may receive a rated traditional policy, while others may find that simplified or guaranteed issue coverage is a more practical option.
Because different insurers use different underwriting guidelines, comparing available policies can be especially useful when you have Type 1 diabetes.
How Diabetes Affects Life Insurance Rates
Having diabetes does not automatically determine your life insurance rate. For traditionally underwritten policies, the insurer will consider your diabetes alongside your age, overall health, lifestyle, and other risk factors.
Depending on your circumstances, different kinds of rates may be available. An insurer may offer a different rate based on your individual medical history and its underwriting guidelines.
What Do Insurance Companies Look At?
When you apply for traditional life insurance with diabetes, the insurer may consider several aspects of your health and medical history, including:
- Whether you have Type 1 or Type 2 diabetes
- Your age when you were diagnosed
- How long you have had diabetes
- Your A1C and blood sugar control
- Your current treatment and medications
- Whether you use insulin
- Your height and weight
- Your blood pressure and cardiovascular health
- Any diabetes-related complications
- Your smoking status and other health conditions
Depending on the application and the insurer, you may also be asked for medical records, laboratory results, or additional information from your doctor.
How to Get Life Insurance If You Have Diabetes
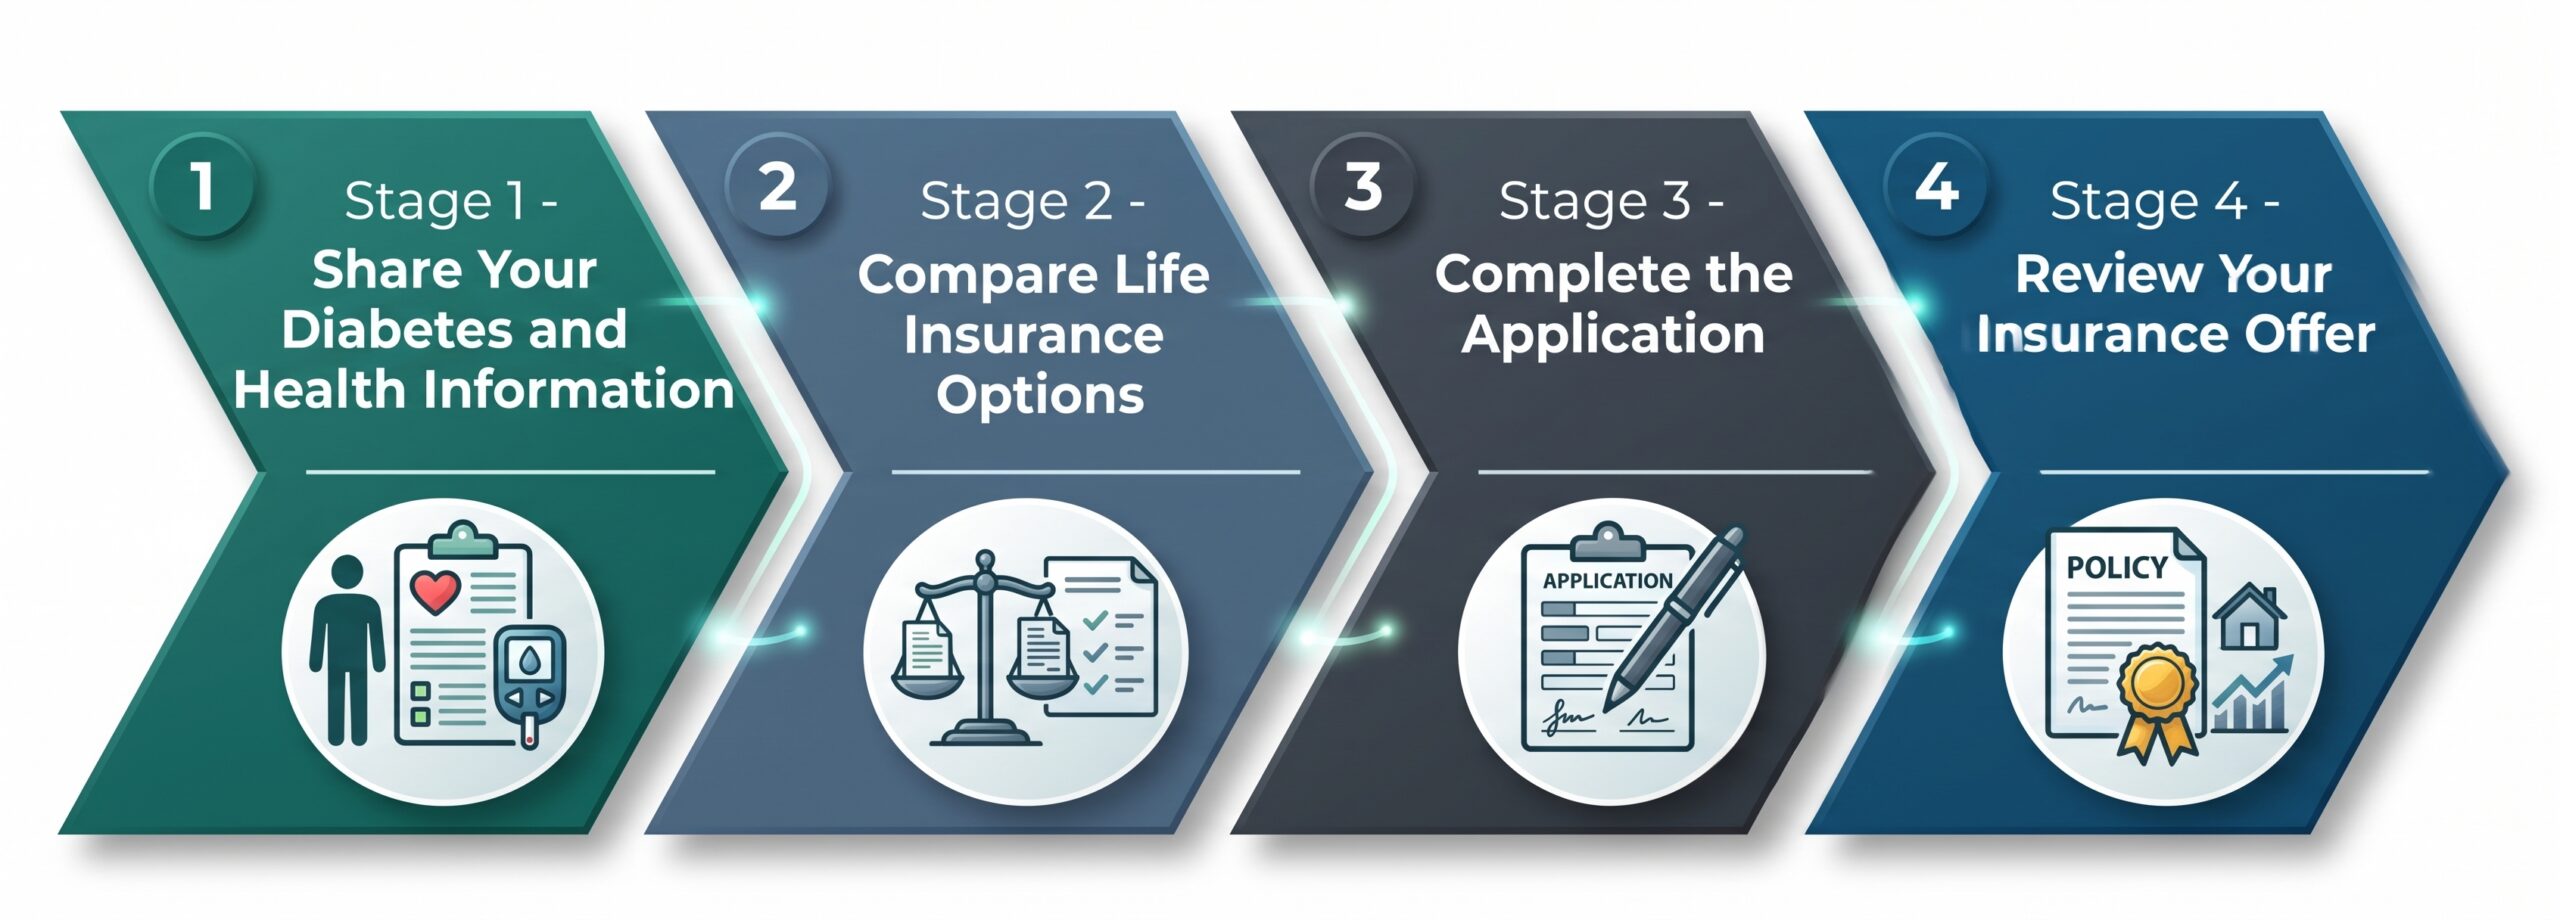
Getting life insurance with diabetes does not have to be complicated. A broker can help you determine which type of policy may be appropriate before you submit an application.
- Share Your Diabetes and Health Information
Start with basic information such as your age, desired coverage amount, smoking status, and the type of life insurance you are looking for.
You may also need to provide information about your diabetes, including when you were diagnosed, whether you have Type 1 or Type 2 diabetes, your current treatment, whether you use insulin, and how well your diabetes is controlled.
- Compare Life Insurance Options
Different insurance companies use different underwriting guidelines. A policy that is unavailable or expensive with one insurer may have a different outcome with another.
An independent broker can compare available insurers based on your individual circumstances and help you identify which types of coverage are worth considering.
- Complete the Application
Once you have identified a suitable option, you can complete the application. Depending on the type of policy, this may involve detailed health questions, medical records, blood tests, a medical exam, or none of these.
- Review Your Insurance Offer
For traditional coverage, the insurer will review your application and determine your rate class. You may receive preferred, standard, or rated coverage, or the insurer may determine that it cannot offer coverage.
If traditional coverage is not available, your broker can help you explore simplified or guaranteed issue alternatives.
How Much Does Life Insurance with Diabetes Cost?
The cost of life insurance with diabetes depends on factors such as your age, coverage amount, policy term, type of diabetes, treatment, overall health, smoking status, and underwriting outcome.
Here are examples of estimated premiums for people with diabetes:
| Applicant | Coverage | Policy | Estimated monthly rate |
|---|---|---|---|
| 44-year-old female, non-smoker, Type 2 diabetes, non-insulin-dependent, diagnosed 5 years ago, stable blood sugar | $250,000 | Term 20 | $56.43 |
| 38-year-old male, non-smoker, Type 1 diabetes, insulin-dependent, diagnosed 7 years ago, stable blood sugar | $500,000 | Term 20 | $123.48 |
| 51-year-old female, smoker, Type 2 diabetes, non-insulin-dependent, diagnosed 10 years ago, stable blood sugar | $200,000 | Term 10 | $93.69 |
These examples are for illustration only and are not guaranteed quotes. Your actual premium may differ depending on your age, health, medical history, coverage amount, policy type, insurer, and underwriting decision.
Get Life Insurance with Diabetes in Canada
Whether you have Type 1 or Type 2 diabetes, there may be more than one way to obtain life insurance.
Complete the quote form to tell us a little about your situation. Our independent insurance brokers work with more than 20 Canadian insurance providers, giving you the opportunity to compare multiple life insurance options instead of applying to just one insurer. We also have experience helping Canadians with pre-existing health conditions find coverage that fits their needs and budget.